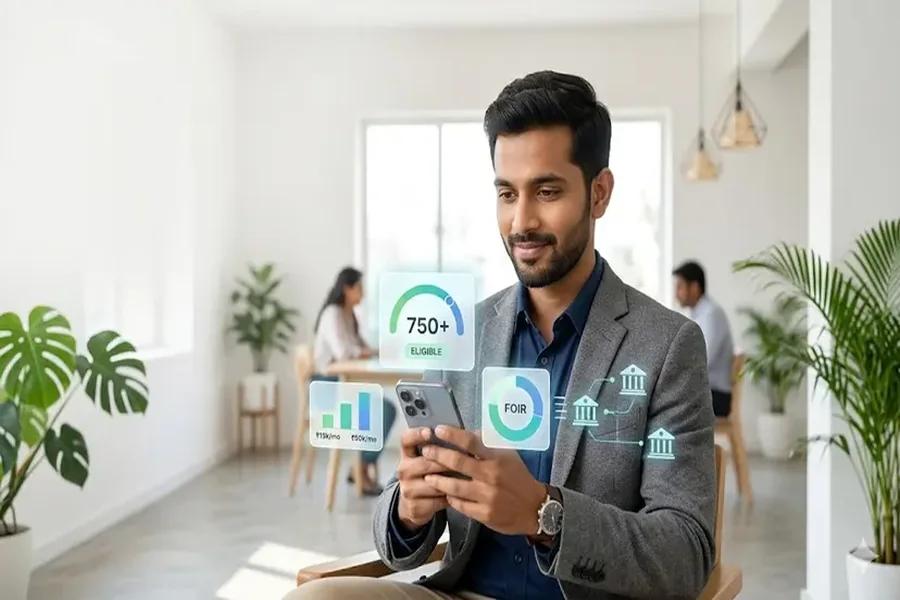
To get a personal loan in Hyderabad, you generally need to earn at least ₹15,000 per month and have a CIBIL score of 650 or more. If you meet these, whether you’re approved will still depend on the specific lender and your financial details. All of these may be considered in the assessment, such as stability of income, employment history, capacity to repay, credit history, and other factors. Knowing these requirements will help salaried professionals to explore the borrowing options that will suit them confidently.
Quick Reads
- The ₹15,000 per month salary could also impact the loan amount and repayment terms offered to the borrower.
- If you are a salaried professional with stable employment and steady income, you can have a strong financial profile.
- They’ll look at what you currently pay each month to work out a figure you’d be happy paying back.
- Choosing the right loan can be aided by comparing interest rates, fees, tenure, and repayment terms.
For a salaried professional in Hyderabad, an unexpected expense may call for additional funds. Whether it is a relocation cost, medical bill, education expense, or home improvement, a personal loan can provide funds without requiring collateral.
Those earning ₹15,000 a month should understand the factors that influence personal loan eligibility. A CIBIL score of 650 or higher can support an application, while lenders may also consider income stability, employment history, existing commitments, documentation, and repayment capacity. Knowing these factors beforehand can help borrowers explore suitable options with greater clarity.
Can You Get a Personal Loan in Hyderabad With a ₹15,000 Salary?
Someone earning ₹15,000 a month could potentially get a personal loan, but it really depends on what the lenders require as a minimum income and how they assess your application. The loan amount and repayment terms can vary as per the applicant’s monthly income and financial profile. Lenders will normally check that the proposed EMI is well within the income and existing financial obligations of the borrower.
The following factors may be taken into account for a salaried applicant earning ₹15,000 per month:
- Monthly take-home pay
- Employment stability
- Existing loan and credit commitments
- Banking and repayment history
- CIBIL score and credit profile
- Requested loan amount and tenure
- Age and other eligibility conditions
Choosing a loan amount that matches the borrower’s monthly repayment capacity can help create a more comfortable repayment plan.
Can a 650+ CIBIL Score Support a Personal Loan Application?
A CIBIL score of 650 and above can help your personal loan application, as it indicates an established credit history. Lenders, in contrast, tend to look at the whole financial profile and not just the credit score.
Other factors like your repayment history, current credit commitments, income and employment information, and recent credit activity can also be part of the assessment. This means that two applicants with the same CIBIL score can have different results in terms of eligibility, depending on their overall financial profile. Reviewing the most recent credit report before applying may be helpful to ensure the information is correct as to the applicant’s financial history. Over time, you can develop a positive credit profile by managing your current credit responsibly and making timely payments.
What Other Requirements Matter for Salaried Professionals?
Lenders look at more than just your salary and credit score when deciding if you can get a personal loan. They also check out other parts of your finances. Knowing what these are will help you get ready and find loans that fit your situation.
Stable Employment
Employment stability can provide lenders with an indication of consistent income. Someone who’s been working steadily usually has a solid income that helps when applying for loans. Different lenders have different rules about employment, so it’s a good idea to check what the specific ones are for the loan you’re interested in.
Repayment Capacity
Monthly income is one part of the assessment, while existing financial commitments can also influence the suitable loan amount.
For example, two professionals earning the same ₹15,000 monthly salary may have different repayment capacities depending on their existing EMIs and regular expenses. Lenders may consider these factors when determining suitable loan terms. Before applying, a borrower can evaluate their own monthly spending plan to determine how much EMI would fit in with their regular spending.
Documentation
You might need documents to prove who you are, where you live, how much money you make, and your job history. What exactly you need can depend on the lender. Things like ID, proof of address, pay stubs, bank statements, and job paperwork are often required. If you keep these common documents ready and current, applying should be easier.
Age and Other Eligibility Conditions
Lenders may also have specific age requirements, minimum income criteria, employment conditions, and documentation requirements. Borrowers can find options that fit their profile by reviewing the relevant eligibility criteria prior to applying, as these requirements may vary amongst financial institutions.
In What Ways Can Salaried Professionals Improve Their Loan Application?
Before exploring a personal loan in Hyderabad, salaried professionals can take a few simple steps to prepare their financial profile. Reviewing their credit history, understanding their monthly budget, and comparing available loan options can help them make a more informed borrowing decision.
A few practical steps can make the application process smoother:
- Review your credit report: Check your latest credit report to ensure that your personal and repayment information is accurate.
- Assess your monthly budget: Consider your existing EMIs and regular expenses to determine a repayment amount that fits comfortably within your income.
- Compare loan options: Look at interest rates, processing fees, repayment tenure, and other applicable terms before choosing a loan.
- Keep documents ready: Having income, employment, identity, and address documents readily available can make the assessment process more convenient.
Conclusion
A personal loan Hyderabad can be a good financing option for salaried professionals earning ₹15,000 per month if the loan amount and repayment plan are aligned with their financial profile. A CIBIL score of 650+ can be supported for the application and income stability, employment history, existing financial commitments and documentation can also contribute to eligibility.
Finnable is a personal loan lender with an online application process and no collateral requirements, ideal for borrowers who want to borrow online. Eligible salaried applicants can choose flexible loan amounts and repayment tenures as per their requirements. After successful verification, loan disbursal can be done in 60 minutes.
You should first look at your credit report to see how much EMI you can manage. It’s also smart to compare interest rates, fees, and loan conditions before you apply. If you think about these points, you’ll be able to find a personal loan that works for your budget and makes paying it back easy.